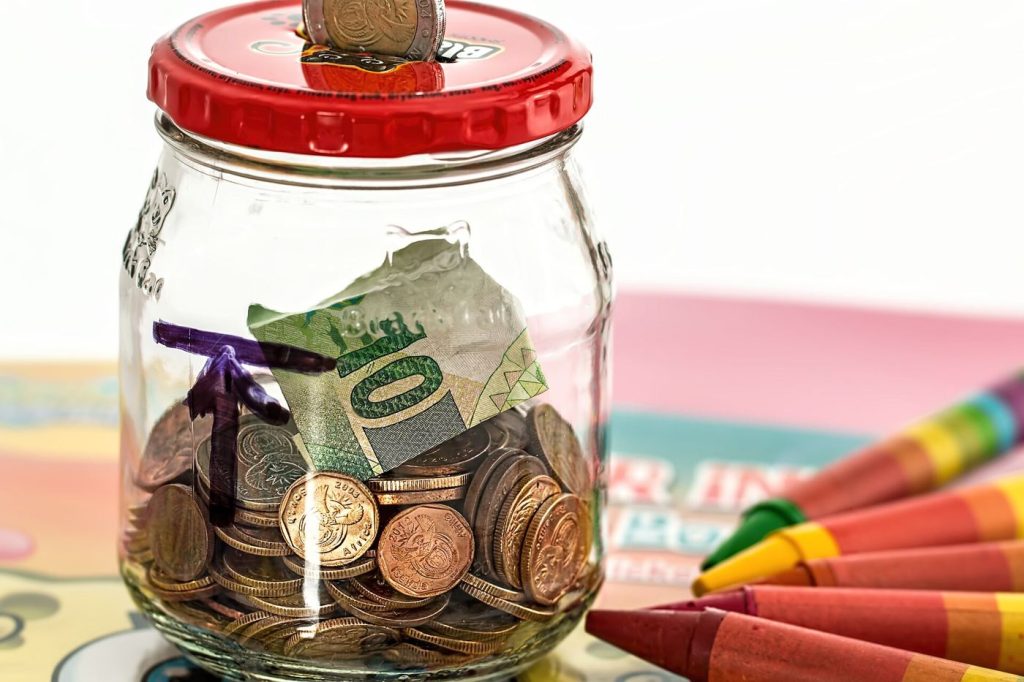
For many households, saving fails not because the intention is missing, but because the decision has to be remade every single week. Automatic transfers solve that problem quietly, moving a modest amount into savings on payday before everyday spending has a chance to absorb it. The amount can start small enough to feel almost invisible, which is precisely why the habit tends to survive busy months and unexpected bills. Over time, those regular contributions build an emergency cushion that can cover a car repair, a broken appliance, or a short gap in income without borrowing. Financial coaches describe it as designing the default, rather than relying on willpower alone.
What the Evidence Shows
Setting the system up takes only a few choices: a realistic amount, a transfer date close to payday, and a separate account that is not checked every day. Reviewing the amount a few times a year helps it grow alongside income, while keeping it flexible enough to pause during genuinely difficult periods. Households also benefit from naming the fund for a purpose, because money set aside for emergencies feels different from money saved for a holiday. The goal is resilience, not perfection, and missing a month does not erase progress. What matters is that saving happens by default, quietly and repeatedly, in the background of normal life. Reporting and analysis from sources such as International Monetary Fund track the same developments, and specialists following small automatic savings building steadily say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by small automatic savings building steadily are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with small automatic savings building steadily will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
There is a practical lesson in all of this for readers deciding what to do today. Start with the verified facts, be wary of anyone promising certainty, and prefer reversible steps while the evidence is still developing. Circumstances differ by country, income and personal situation, so general guidance should always be weighed against your own context before you act on it in any significant or lasting way.
